

Xoom: Send Money & Transfer

- 30.30K Reviews
- 4.8
- Downloads
- 5,000,000+
Our take on Xoom: Send Money & Transfer from Appgk
Sending money across borders is one of those tasks that sounds simple until I actually need to do it. The recipient may need the funds quickly, the sender wants a clear total before confirming, and nobody wants to guess whether a transfer will arrive in a bank account, be collected in cash, or require another step. My main focus when reviewing Xoom was therefore its central job: helping people send money from their phone to family, friends, or other recipients in another country.
Xoom: Send Money & Transfer is a free finance app from Xoom, a PayPal Service. It supports transfers to Mexico, India, and 145 countries, which makes it more useful than a service built around only one popular corridor. I found the app most convincing when I treated it as a practical remittance tool rather than as a general-purpose banking replacement. It is designed to move money internationally, not to manage every part of my financial life.
The app is available to Everyone, runs on operating systems from version 10 onward, and its current version is 10.11.0. It has been around since Aug 8, 2012, and its reach is reflected in more than 5 million installs. A 4.8 average from roughly 363 thousand ratings and about 30 thousand reviews suggests that many users find the basic experience dependable, although a strong store rating should never replace checking the details of a particular transfer.
Why the transfer capability matters in everyday use
The useful idea behind Xoom is not merely that it sends money internationally. The real benefit is that it brings the decision-making process onto the phone, where I can enter the recipient and amount, review the transfer, and choose the destination method available for that route. That matters when I am sending support to someone who does not use the same bank or financial app that I do.
Best Parts of Xoom: Send Money & Transfer
Things to Keep in Mind About Xoom: Send Money & Transfer
In a typical situation, I might be living in one country while a parent, sibling, or friend is elsewhere. A traditional bank transfer can feel excessive for a modest family payment, especially if the recipient needs a different way to receive it. Xoom is aimed at that gap. Its country coverage gives it a practical role for recurring personal remittances, emergency help, and occasional payments to people abroad.
I also like that the app makes the transfer itself the center of the experience. I do not have to learn a broad investment platform or navigate unrelated financial products just to reach the international-send function. That focused design can reduce mental clutter, particularly for someone who sends money only a few times a year and wants the steps to be understandable.
News and Features Related to Xoom: Send Money & Transfer

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
There is an important distinction, though. International transfer apps are not interchangeable. Some alternatives are strongest for holding balances in several currencies, some are aimed at frequent business payments, and some are tied closely to a particular bank. Xoom makes more sense when the priority is sending money to a person in another country through a service built specifically around remittances. It may be less suitable if I want a full multi-currency account, detailed spending tools, or a long-term way to organize money across countries.
What I check before pressing send
My safest habit with this kind of app is to treat the review screen as part of the transaction, not as a formality. I check the recipient’s name, destination country, amount, and receiving method carefully. A small mistake in a recipient detail can create unnecessary delays or support work, so I would not rush through the final confirmation simply because the transfer feels familiar.
Don't want to read the full review?
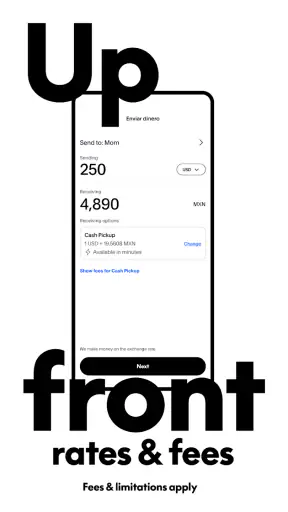
I also look at the total cost and the amount the recipient is expected to receive. The amount sent is not always the same as the amount delivered, and exchange rates or transfer charges can affect the result. Even when the app presents the information clearly, I would compare the final figure with another service if the transfer is large or if the recipient needs a very specific amount.
That comparison is one of the less obvious ways to use Xoom intelligently. I would not compare only the headline fee. I would compare the complete outcome: what leaves my account, what reaches the recipient, and how convenient the receiving method is. A supposedly cheaper option may be less useful if it forces the recipient to travel, wait longer, or use an account they do not have.
Screenshots
How the process feels in practice
The basic workflow is familiar: select the destination, enter the transfer information, identify the recipient, review the transaction, and submit it. The value comes from having those decisions arranged around an international remittance rather than making me assemble the process through separate banking screens. For a first-time user, I would still read every label carefully, especially when the recipient has more than one possible way to receive funds.
One practical tip is to prepare the recipient’s details before starting. I would confirm the spelling and the preferred receiving route with the person first, rather than beginning the transfer while messaging back and forth. This is especially helpful when sending to someone who expects a bank deposit but could also use another collection method. The app can make sending convenient, but it cannot decide which recipient information is correct for me.
Another useful workflow is to use the app for a small, planned transfer before relying on it for a larger urgent payment. That lets me understand the confirmation screens and the recipient’s side of the process without adding pressure. It also reveals whether the selected receiving option fits the person’s real circumstances. Convenience on the sender’s phone is only half of a successful remittance.
The app’s security positioning is reassuring, and the association with Xoom, a PayPal Service, gives the product a recognizable financial-services context. Still, I would protect my account as carefully as I protect online banking. I would avoid sending from a shared device, verify messages claiming to relate to a transfer, and never treat an unexpected request for payment details as trustworthy merely because it uses the app’s name.
A realistic family-support example
Imagine that I work abroad and send money home near the end of the month. My brother needs the funds for household expenses, but he does not want to depend on the same bank I use. I can open Xoom, select his country, enter the amount, choose the receiving route that suits him, and review the total before completing the payment. The important advantage is not just speed; it is being able to match the transfer with his actual access to money.
In that scenario, I would message him first and ask whether he wants the funds deposited or collected through the available option for his location. I would then confirm the details on my side and save the transaction information for my own records. If the payment is recurring, I would keep a consistent routine: verify the recipient, check the delivered amount, and avoid assuming that a previous setup should be repeated without review.
For an emergency, the same focused design can be valuable. If a relative needs help with an unexpected expense, I may not have time to explain a complicated financial platform. Xoom’s purpose is easier to understand: send money internationally through the app. But urgency is exactly when I would slow down at the final step, because a rushed transfer to the wrong person is much harder to fix than a delayed confirmation caused by checking carefully.
The tradeoffs behind convenience
The first tradeoff is cost versus simplicity. Xoom can save me from arranging an international payment through a conventional bank, but that does not mean every transfer will be the cheapest available route. The right comparison depends on the country, amount, currency conversion, and receiving method. I would use the app’s displayed total as the starting point, then compare it with a bank or another remittance provider when the difference matters.
The second tradeoff is coverage versus local fit. Supporting 145 countries is broad, but country coverage alone does not tell me whether the available receiving method is ideal for a particular person. Someone in a city with easy access to the selected method may have a smooth experience, while someone in a rural area may prefer a different route. I would choose based on the recipient’s practical access, not simply on whether the country appears in the app.
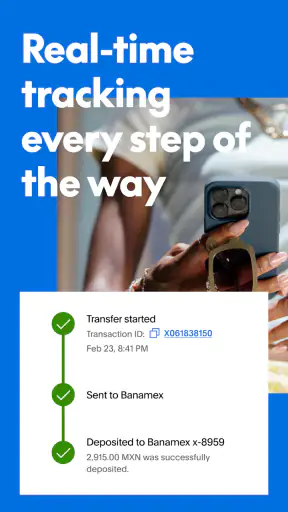
The third tradeoff is speed versus certainty. A recipient may want money immediately, but I would not promise a precise arrival time before checking the transfer details shown for that transaction. Processing can depend on the route and the recipient’s circumstances. For rent, medical costs, tuition, or another deadline, I would send earlier than the last possible moment and keep the confirmation available.
There is also a human limitation: the app cannot remove the need for accurate communication between sender and recipient. If the recipient changes phone numbers, bank details, or preferred collection arrangements, I need to update my own plan rather than assuming that a previous transfer pattern remains correct. Xoom simplifies the sending interface; it does not replace common sense or careful coordination.
Where it compares well with usual alternatives
Compared with sending money through a conventional bank, Xoom feels more purpose-built for personal international transfers. A bank may be the better choice when both people already use the same institution, when a formal account-to-account relationship is important, or when I need broader banking records in one place. For a family remittance to a different country, however, a dedicated app can be easier to approach.
Compared with a service focused on multi-currency balances, Xoom is more direct when my goal is to send money to another person rather than hold and manage currencies myself. A multi-currency alternative may be better for someone who travels constantly, invoices clients in several currencies, or wants to keep funds available for later spending. I would choose Xoom when the destination is a recipient, not when I am building an international wallet.
Compared with cash-based remittance shops, the phone-based workflow is more convenient for me because I can begin the transfer without visiting a counter. That convenience may be less important to a recipient who prefers face-to-face help or does not use smartphones comfortably. In that case, the best service is the one that works for both sides, even if it is not the most modern-looking option.
The app’s large user base and high average rating make it easier for me to consider as a mainstream option rather than an obscure transfer tool. I still would not use popularity as a reason to ignore the transaction summary. A well-known service can be appropriate and still require careful checking for each country and receiving method.
Who will get the most from Xoom
I would recommend Xoom first to people who regularly support family members abroad, send occasional personal payments, or need a straightforward mobile route to a recipient in one of its supported countries. It is particularly appealing when the sender and recipient use different financial institutions and when the recipient needs flexibility in how the money is received.
It can also suit someone who is new to international remittances and wants a focused app rather than a large banking platform. The free download lowers the barrier to trying it, while the Everyone rating makes it broadly accessible from a content-rating perspective. I would still make sure the phone meets the operating-system requirement and that the intended destination and receiving method fit the transfer.
I would be more cautious about recommending it to a user whose main goal is minimizing cost on every transaction. That person should compare the complete delivered amount with specialist alternatives and bank options each time. I would also point frequent international traders, businesses with complex payment needs, and people seeking a full currency-management account toward services designed around those jobs.
Someone who dislikes entering financial information on a phone may prefer a bank branch or another assisted option. Likewise, if the recipient has limited digital access, the sender should prioritize a receiving method the recipient can actually use. The strongest feature of Xoom is only valuable when both ends of the transfer are practical.
My final view after using it as a remittance tool
Xoom succeeds because it keeps international money sending at the center of the experience. I found the broad country reach, mobile workflow, and recipient-focused approach more meaningful than a long list of extra financial functions would have been. For a family payment, the app can turn a complicated cross-border task into a sequence I can review and complete from one place.
My recommendation comes with a clear condition: use it deliberately. Confirm the recipient, inspect the total, compare the delivered amount when cost is important, and choose the receiving method around the person who will actually collect or access the funds. Those habits matter more than simply finding a button that says send.
For me, the app is at its best when the need is specific and personal: helping someone abroad, making a planned remittance, or sending support without setting up a larger international banking arrangement. It is not the universal answer for currency management or for every business payment. But if that focused need matches yours, Xoom: Send Money & Transfer is a practical option worth considering, especially when convenience and recipient access matter as much as the transfer itself.
Xoom: Send Money & Transfer FAQ
What is Xoom: Send Money & Transfer, and how does it work?
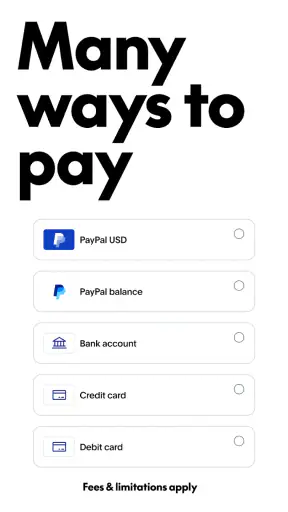
Xoom is a PayPal service that lets users send money internationally, pay bills, and sometimes reload mobile phones or arrange cash pickup, depending on the destination country. After creating an account, you select the recipient, enter the amount, choose a delivery method, and review the exchange rate, fees, and estimated arrival time before confirming the transfer.
Is Xoom safe to use for international money transfers?
Xoom uses security measures associated with PayPal, including account protection, transaction monitoring, and identity verification. However, no financial service is completely risk-free. Before sending money, check the recipient’s details carefully, use a secure connection, and never share passwords or verification codes. Transfers may be difficult or impossible to reverse once the recipient receives the funds.
How much does Xoom charge, and what exchange rate will I receive?
The total cost depends on the sending country, destination, payment method, transfer amount, and delivery option. Xoom may charge a transaction fee and include a margin in its exchange rate. The app normally displays the recipient’s expected amount, applicable fees, and exchange rate before you authorize payment, so review the final summary rather than relying on an advertised starting price.
How long do Xoom transfers take, and where can recipients receive money?
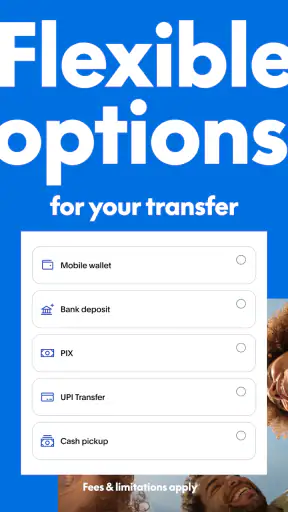
Delivery times vary by destination, funding method, transaction review, weekends, holidays, and local banking schedules. Some transfers arrive quickly, while bank deposits can take longer. Depending on the country, recipients may receive money in a bank account, mobile wallet, or through a participating cash-pickup location. Xoom shows an estimated delivery time during the transfer process.
What do I need to use Xoom, and can a transfer be canceled?
You generally need an eligible account, accurate personal information, a supported payment method, and the recipient’s correct details. Xoom may request identity or source-of-funds verification, particularly for certain amounts or destinations. Cancellation depends on the transfer status: a pending transaction may be eligible, but completed transfers are usually difficult to cancel or recover.











